Why PEO All-In PEPM Pricing Looks Cheap Until You Strip Out What a Broker Does for Free
Hidden markups and embedded fees make PEO pricing less transparent than it appears.
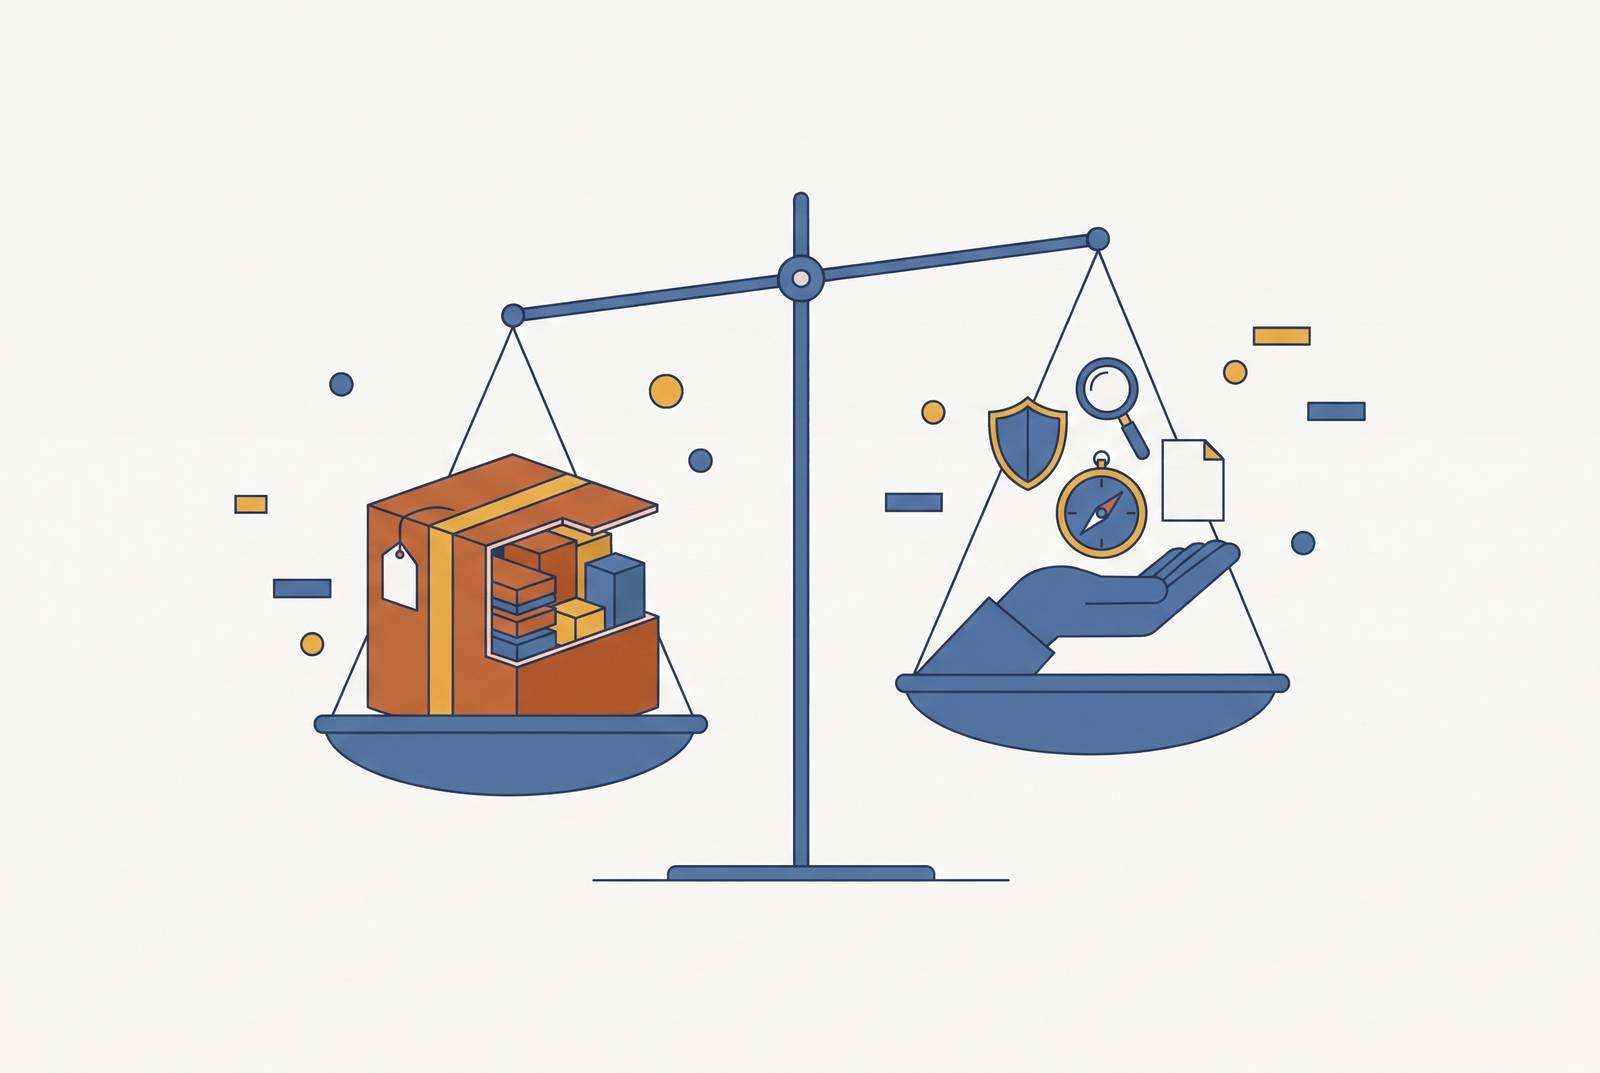
A PEO’s per-employee-per-month administrative fee is not its total per-employee cost. A commission-paid benefits broker typically charges the employer no direct service fee, although its commission is built into insurance premiums. The comparison therefore turns on total costs and responsibilities, with PEO pooling strongest for very small groups and direct brokerage more attractive as employers gain negotiating scale.
What the PEPM number actually is — and what it leaves out
One line, one vendor, one bill makes PEO pricing look manageable. That simplicity is useful, but it is incomplete. The administrative fee is only one component of the employer’s payment, with health insurance, dental and vision premiums, workers’ compensation, and payroll taxes billed on top. Calling the administrative charge “all-in” makes the scope of the quoted number the first question in any comparison.
PEOs use two pricing models, namely flat PEPM and percentage-of-payroll charges. The flat model links the administrative fee to headcount, while the percentage model links it to compensation. As merit increases lift average salaries, percentage-based fees rise automatically even when the PEO’s responsibilities stay the same. For technology companies with highly paid engineering teams, higher wages can raise the cost of administration even if they add no employees and the work stays the same.
The fees embedded in PEPM that the invoice never names
The most consequential additional cost is the health premium markup. PEOs commonly apply a markup to health insurance pass-through charges, and employers rarely see it disclosed upfront. The premium line is therefore not necessarily a transparent statement of the underlying insurance cost. This complicates a comparison with a direct plan because the employer must distinguish the price of coverage from the amount retained through the PEO arrangement. The bundle itself creates this difficulty regardless of the vendor’s intentions.
Another cost that is harder to see comes from Section 125 cafeteria plans. When employees pay health premiums pre-tax through such a plan, the employer owes less in FICA on those contributions. Under PEO co-employment, that saving often goes to the PEO rather than back to the employer, although some contracts can be negotiated to return it. The contract determines who receives the benefit. Percentage-of-payroll charges based on gross payroll rather than the Section 125-reduced base compound the disadvantage, because the employer forgoes the FICA saving while paying an administrative fee on the unreduced amount.
Leaving can bring costs that do not show up in the monthly figure. The terms for early termination can make leaving expensive, while switching payroll mid-year can restart Social Security tax withholding as though employees had changed employers. These costs arise at departure rather than during ordinary monthly billing. They nevertheless belong in the economic comparison because the employer may eventually need to change arrangements. A direct broker model makes the distinction between insurance premiums and broker compensation clearer, but it does not remove the need to examine separate administration and transition costs.
What a benefits broker delivers — and what it costs the employer
A commission-paid benefits broker typically receives compensation from the carrier, with the commission built into the insurance premium. The employer generally pays no direct fee for brokerage services under that model. Carrier-paid compensation is one payment structure, and fee-based and hybrid arrangements also exist in which the employer pays the broker directly. “No direct cost” is therefore the precise comparison, rather than a claim that brokerage has no economic cost.
At annual renewal, the broker gets competing bids from multiple carriers and uses plan design analysis and benchmarking to compare benefits with those of peers by company size, geography, and sector. Open enrollment support includes employee communications and enrollment platform management. The broker can also help with compliance through ACA reporting, ERISA plan documents, COBRA administration oversight, and Form 5500 coordination. These are broker-equivalent functions that an employer may already receive within a PEO bundle without seeing a separate price for them.
Moving to a commission-paid broker therefore does not, by itself, create a new direct brokerage charge. The employer stops paying the PEO administrative fee, while the broker is still paid through the premium. Scope still needs a separate comparison. A benefits broker is not a substitute for every payroll or employment function in the PEO arrangement, so treating the entire PEPM fee as a benefits-only saving would overstate the case. The comparison starts with the direct plan premium plus the cost of any separate services needed to take over the PEO’s other work.
That distinction also governs comparisons with AI-native benefits platforms. A traditional broker’s commission arrangement and an AI-native brokerage’s service model must each be considered on their stated terms, including any direct fees and third-party charges. Without those terms, a per-employee cost comparison would look more exact than the known fees allow.
The plan control and carrier access a PEO forecloses
Under co-employment, the PEO is in charge of the health plan relationship. It selects carriers, sets plan designs, and manages renewal, leaving the employer outside the direct carrier relationship. If the PEO’s master rates rise, the employer’s choices are to accept the increase or leave the PEO. That restriction follows from the structure of the arrangement. It is not a claim about whether an individual PEO negotiates well or acts in its clients’ interests.
A broker working with a direct plan gives the employer a different set of options. As the business grows, the broker can pursue level-funded or self-funded arrangements. PEOs rarely offer those alternatives. Even when they do, the employer cannot take the plan relationship with it upon departure. The difference therefore concerns both the options available at the next renewal and whether the employer retains that relationship through a later change in service provider.
An employer with favorable claims history inside a PEO’s large-group pool receives the PEO’s standard renewal rather than a renewal that directly rewards its own experience. Its favorable results support the pool. On a direct plan, a broker can instead use that history on the employer’s behalf at renewal, with the advantage becoming more meaningful as headcount makes the claims data statistically credible. For a CFO, the cost is the forgone opportunity to translate favorable claims into employer-specific renewal economics.
Where PEO buying power genuinely wins — and when that advantage expires
PEO pooling can produce genuinely lower premiums for very small employers. Below roughly 50 employees, access to a large-group plan can yield a lower per-employee insurance cost than a broker can negotiate in the small-group market. This is the strongest case for the PEO. Small companies in the pool can avoid age-banded medical ratings and get composite rates that they would otherwise need large-group status to get. A broker’s lack of a direct service fee does not automatically outweigh that premium advantage.
That concession changes how the comparison should be read. The lowest administrative charge is not necessarily the lowest total cost, just as the lowest premium does not settle the whole decision. At small headcount, the pooling benefit can justify paying for the PEO wrapper. The employer is purchasing access it may not otherwise have, as well as administration. Treating that access as worthless would make the argument against bundled pricing as incomplete as accepting the headline PEPM figure at face value.
Above the small-group band, the premium advantage diminishes while the PEO administrative fee persists. The employer can then be paying for pooling it no longer needs while surrendering plan control and the benefit of its own claims experience. Headcount provides a benchmark whose relevance varies by employer. In the 50–100 employee band, employers should start modeling whether they would get better value overall through direct negotiation, FICA offset recapture, premium markup elimination, and more freedom in plan design.
Compliance obligations that transfer to the employer when the PEO relationship ends
Leaving a PEO changes operational responsibility. The employer still needs the relevant work performed, whether the provider is a PEO, a broker, or a separate administrator. Continuity depends on assigning that work explicitly. A credentialed broker’s compliance services can replace benefits-related functions that the PEO handled, but the replacement must be assessed by task rather than by a broad promise of “compliance coverage.”
The ACA employer mandate applies at 50 full-time equivalents and requires minimum-value, affordable coverage for nearly all full-time employees. ERISA requires an audit each year, attached to Form 5500, once a plan has more participants than the threshold allows. COBRA continuation coverage also requires attention to election notice timing, with ERISA civil penalty exposure making the handoff more than a routine enrollment task. These duties do not end with the contract. Their administration must continue through the change in plan and service relationships.
Broker coverage commonly includes ACA reporting, ERISA plan documents, COBRA administration oversight, and Form 5500 coordination. When the broker is paid through commission, the employer may pay no extra line-item charge for those services. Oversight and execution are not always the same. Separate third-party administrators may charge for COBRA administration or Form 5500 preparation, and fee-only brokerage arrangements can also create direct charges.
Employers must also follow final paycheck laws. State-by-state differences make offboarding a compliance event, with timing requirements that vary sharply across jurisdictions. That responsibility cannot be assumed to sit within benefits brokerage merely because the broker handles ACA or ERISA work. The plan for leaving must name who will handle payroll-related compliance as well as benefits administration. Leaving the PEO need not mean losing coverage, but neither model eliminates the employer’s need to know who performs each function.
Timing the transition — why the exit window and the renewal calendar are the same decision
The PEO exit and benefits renewal should be planned as one decision. A January 1 exit aligns with open enrollment and avoids the mid-year payroll disruption associated with restarting Social Security tax withholding. Mid-year restarts can create temporary employee cash-flow disadvantages, even though those amounts can be reconciled when employees file their annual returns.
The modeling should begin in the 50–100 employee band, before the current carrier presents its renewal. A broker should first benchmark benefits against the market so that the employer enters negotiations with independent evidence rather than the PEO’s composite rate as its only reference point. This establishes a usable negotiating baseline. The comparison should account for the loss of the PEPM charge, potential FICA offset recapture, removal of premium markups, and the value of more flexible plan design. Any separately charged replacement services also belong in that calculation.
The operational planning window should then include a state-by-state payroll registration review. After exit, the employer must hold its own registrations in every state where it has employees, so that work belongs in the departure plan. The handoff should also make clear who will take over COBRA, ERISA plan documents, and Form 5500. Each function needs a clear operational owner. That allocation connects the financial decision to the services required to make the new arrangement workable.
The final distinction is between completing the exit and managing what follows. A January 1 transition settles when to exit, but benefits compliance remains ongoing work. The broker relationship must therefore cover more than placement and renewal. An AI-native brokerage handles the ongoing monitoring that makes the post-PEO compliance surface manageable without adding headcount.